As a market research company specialized in the tank terminal business we truly value the FETSA and its members. Europe is our home base so this makes it even more logical to become a supplier partner. With this partnership we want to underline the long term commitment to FETSA members to improve their markets by providing insights and enabling intelligent decisions.
Patrick Kulsen, Managing Director of Insights Global
Download FETSA brochure that contains key figures on Tank Terminals in Europe
Uit cijfers van EY (2015) bleek dat in Nederland ongeveer 16.000 mensen werkzaam waren in de olie en gasindustrie. In hetzelfde jaar in Amerika waren dat zelfs bijna 1.5 miljoen mensen! Hierbij zijn nog niet eens de dienstverlenende bedrijven meegeteld. Het is dus een immense sector!
Het is niet alleen groot qua omvang maar ook qua complexiteit. Veel bedrijven die we tegenkomen begrijpen slechts het onderdeel van de logistieke keten waarin zij actief zijn. Zij missen kennis van de gehele logistieke keten. Juist die andere ketenonderdelen hebben vaak directe impact op de winstgevendheid van hun business.
Een aantal van deze organisaties hebben bij ons de tweedaagse Oil Academy gevolgd. Na de training zijn zij zich beter bewust van hoe de gehele olie -en gas waardeketen functioneert. Zij begrijpen beter hoe de verschillende marktspelers en fundamentals werken. Al bijna 200 deelnemers gingen u voor en waardeerden deze training met meer dan een 8!
Voor meer informatie, vraag onze Oil Academy brochure aan door het onderstaande formulier in te vullen.
Our colleague, Jacob van den Berge, active as IG’s Marketing and Sales Manager and oil market analyst will be representing our company in the States, birthground of the modern oil industry.
Especially for the NISTM visitors, Jacob will give a presentation about the US tank storage market focussing on storage players and market outlook. Every day of the conference at 11AM at his stand #814. After each presentation, participants are able to access the slides.
IG’s conceptual model shows relations between market circumstances and a terminal’s commercial performance. In this model market fundamentals drive market dynamics. A terminal that has a good fit to these market dynamics will find that their storage rates are supported.
Apart from this direct relation between tank terminal characteristics, market dynamics and storage rates, there is also a relation between market fundamentals and storage rates.
The distinction between market fundamentals and market dynamics lies mostly in the difference in rate of change. Market fundamentals tend to be more stable compared to market dynamics.
Market dynamics have a direct relation to operational activities at tank terminals. Main focus points are related to market fundamentals: logistics, forward curve outlook and competitive structure. Furthermore, expected impact on market dynamics and corresponding tank terminal operations will also be taken into consideration.
Since the beginning of 2000, Insights Global has been involved in numerous consultancy assignments.
These ranged from market studies of specific sectors such as the chemical, wholesale and retail, tank storage, trading and shipping, and oil industry.
Also, different regions have been covered such as Northwest Europe, Mediterranean, ARA, Singapore, and the US.
Since 2014, Insights Global has been heavily involved in due diligence projects of storage assets, specifically commercial DD. Some of these were part of the winning bid.
To say that the global tank terminal business is large is an understatement. There are more than 4900 tank terminals comprising more than 1 billion cubic meters of storage capacity. The business has grown at a compounded annual growth rate of 3% since 2005 and in coming years another 10% will be added to global tank capacity. Some might argue that capacity has grown too fast and that we are approaching a situation where markets are ‘over-tanked’. But is this really the case? This is a very relevant question for many players. For instance, if you are a business development manager at a terminal operator you need to understand this because it can guide you in determining if and where to invest. Another example are investors. If you are an investor in infrastructure assets you need to understand this in order to decide on investing or divesting in and valuating terminal assets.
Every terminal essentially has a logistics or hub function. This is the prime function. Some terminals are also used as a trading platform by its clients. Physical commodity traders require terminals for their business model. The last function a terminal can have is to store crude or oil products as part of a country’s strategic petroleum reserves. This last function is interesting for a specific terminal operator but from an economic analysis point of view less relevant because it is dependent on specific policies defined by governments. We therefore leave this function outside of the scope of this article.
So we will focus of the logistics and trading platform functions. After careful analysis of these functions and the value it can bring to clients of terminals we concluded that there are three key factors that act as business indicators for tank terminal markets:
Commodity price dynamics
Inventory levels
Trade flows
If you are analyzing business at a specific terminal you need to look at these factors in the local context. However, for the purpose of this article we have looked at these factors on a global scale and we have focused on oil markets.
Oil price dynamics
Current oil price levels are low and rather volatile. The low price levels stimulates demand and the increased volatility creates trading opportunities. The forward curve is downward sloping (backwardation) which weighs on arbitrage opportunities. However, some institutions like the EIA are forecasting a slight oversupplied global crude market, which could soften the backwardation or even flip it to a contango, which would be good news for the terminal sector.
Inventory levels
Global crude and oil product inventories are on the lower end. This is related to the backwardation price structure. So tanks are slightly underutilized right now.
Trade flows
Global crude and oil products
trade flows have been increasing at a steady rate in the last decade. This rate
resembles the growth rate in tank capacity and thus signals that the balance
between tank capacity and tank demand is more or less balanced. This is a very
positive sign.
The main conclusion from the above analysis is that the global market does not seem to be over-tanked and that the current situation is set to improve significantly after oil price dynamics change to fully support the terminal business. So the future is definitely bright for the terminal business!
About the author
Patrick Kulsen is Managing Director and Senior Consultant at INSIGHTS GLOBAL, a market research company specialized in oil and petrochemical markets. The company’s consultancy team has successfully helped clients with research and commercial due diligence projects for many years. For more information on our consultancy services please follow this link.
In the last decade the tank terminal markets has seen quite a large number of Merger & Acquisition deals. One of the main trends that has been witnessed is that investments funds are stepping in and in many cases are emerging as winners of these bids. As an investor or fund manager you might wonder “Is the tank terminal sector worthwhile getting into?” or “Is the opportunity at hand going to diversify my investment portfolio?”. This blog post will try to give guidance on this subject.
Infrastructure Asset Class
Tank storage assets, due to their resilient and stable revenue profile are considered infrastructure assets. Such assets are attractive investments if it fits the risk/return profile of your fund. Nevertheless there are some nuances that need to be made. Not all terminals are alike so a more detailed approach is needed to distinguish between various groups of terminals. From an investment portfolio perspective it is sensible to group terminal assets into different categories based upon their exposure to business risks.
1. Location, location, location…
One obvious
characteristic is the location of the terminal. For one, country risk is
associated with the location of the terminal. Is the terminal located in an
OECD country or not might be a good way to look at this. However location of
terminals has many more implications. It is the single largest factor driving
value of terminal assets due to various reasons. Most likely if you ask experts
the question “what is are the three most important terminal characteristics”
they’ll answer “location, location and location”. So the conclusion is that a
thorough analysis of the implications of terminal location is needed.
A rather simplistic but effective first order categorization is to group terminals into Hub Location and Non-Hub Location terminals. The hub location terminals are well positioned and are better able the weather downturns in business cycles. Additionally, these terminals are less sensitive to local and regional economic circumstances. Business activity at hub terminals is related to global trade, which is less volatile and thus has a lower risk profile.
Another categorization method is to distinguish between sea-access and inland terminals. This grouping has some overlap with the functional categorization that will be discussed in the next section. Nevertheless it gives additional insights into the risk profile because sea-access terminals offers more flexibility for its customers and has a larger operating region. On the other hand, inland terminals are more restrictive and are in most cases confined to the local area. This doesn’t mean that these assets are worthless, they can be very profitable. However, they do have a different risk profile.
2. Market Segment
After location the second question you need to ask is: what liquid products are stored at the terminal? Products can be categorized into the following main groups: crude oil, petroleum products, pressurized gasses (such as LPG), LNG, chemicals, vegetable oils, bio-fuels and others. For petroleum products and chemicals sub-categories apply, but let’s not overcomplicate matters here. The point is that for instance petroleum product markets have a different dynamic than chemical markets. This translates to a different risk profile for the terminal business. So market segments are a key characteristic.
3. Terminal Functions
A tank terminal can
have one or more functions for its clients. These functions are driven by
business environment and the infrastructure of the specific terminal. The main
functions applicable to terminals are:
-Logistics / hub function:
o Make /break bulk hub
o Distribution & inter-modality hub
o Integration with industrial site
o Bufferstock
-Trading platform:
o Physical arbitrage
o Blending
o Contango storage
o Optionality
-Strategic storage
Uncovering dominant
functions related to the specific terminal that is up for sale gives insights
into its business and the related risks.
Putting it together: does it fit?
By combining the above
mentioned locational, market segment and functional aspects the terminal asset
can quickly be profiled to see if it contributes to the diversification of your
portfolio. A diversified terminal asset portfolio should preferably have a
variety of assets that ranges across different locations, markets segments and
incorporates a varied set of functions. If too many assets are in the portfolio
that have similar risk profiles the portfolio might be too exposed to a certain
risk.
The above mentioned
characteristics have the ability to frame the asset. But please keep in mind
that a more detailed approach is required later on in the process as part of
the commercial due diligence project.
Terminal Portfolio Compatibility Call (FREE)
The above described methodology gives an outline of an approach that can be applied to check if a terminal asset fits your investment portfolio. However, elaborating on all relevant details is outside the scope of this article. Additionally a lot of data is needed to profile terminals. So you might need help to fully implement this method. We can help you with this. Please contact me for a freeandconfidential terminal portfolio compatibility call. In this call, I will apply this method to your investment opportunity so you have instant insights into the risk profile.
About the author
Patrick Kulsen is Managing Director and Senior Consultant at INSIGHTS GLOBAL, a market research company specialized in amongst others commercial due diligence of tank terminals. The company’s consultancy team has successfully helped clients during M&A projects for many years. For more information on our consultancy services, please follow this link.
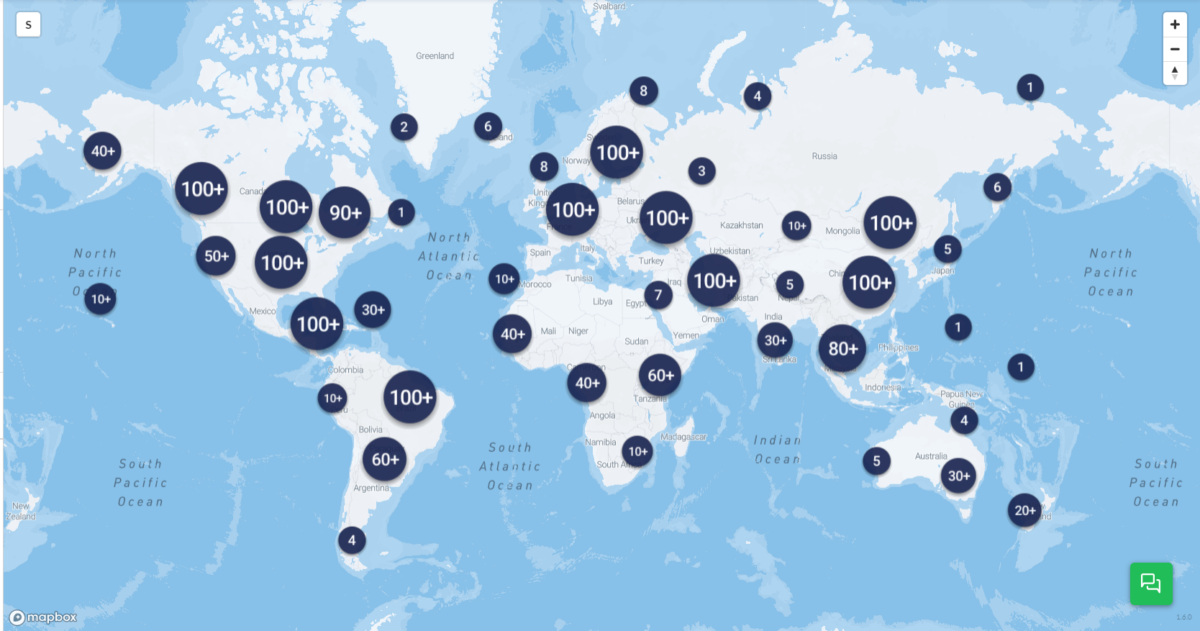
In the world of international tank storage, thousands of terminals give access to commercial storage. These terminals are located all over the world. From large tank farms in oil trading hubs in ARA, USGC, Fujairah and Singapore to small depots on Guam or Greenland.
The tank storage sector is not a static industry but a dynamic one which grows every year. It is interesting to find out which regions have the most investments planned or are currently building new additions.
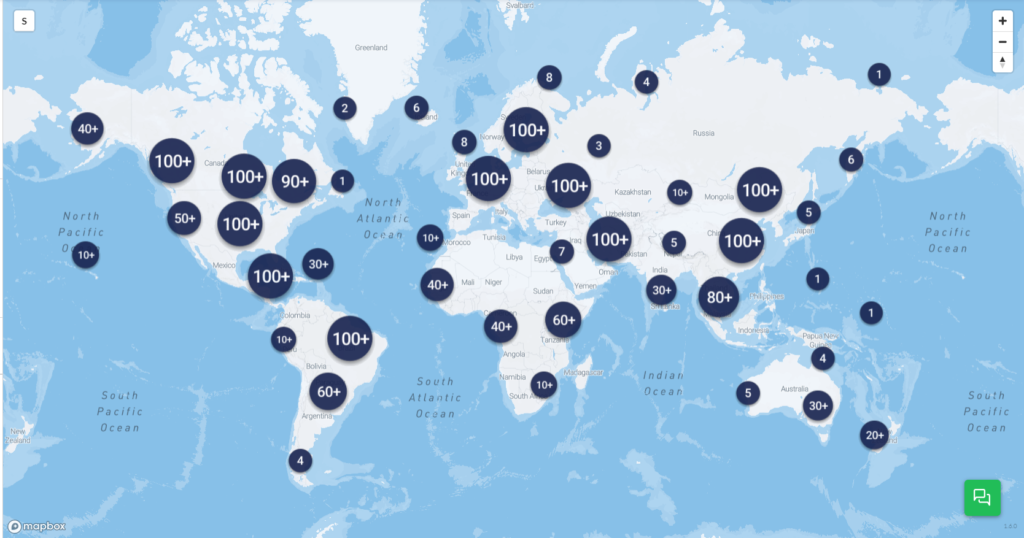
In picture 1 can be seen where the largest concentrations of tank terminals are.
The world’s hottest storage hotspots
Estimates are that global tank storage capacity will grow 8% to 1.03 billion cbm in 2020 and even 11.5% to 1.06 billion cbm in 2021.
When ranking the regions with the largest total tank capacity in 2019 the following list can be produced: 1) Asia (360Mcbm), 2) Europe (235Mcbm), 3) North America (191Mcbm), 4) Middle East (50.8Mcbm), 5) South America (45.5Mcbm), 6) Africa (43.6Mcbm), and 7) Oceania (4.4Mcbm).
In 2020 the ranking is as followed: 1) Asia (383.7Mcbm), 2) Europe (244Mcbm), 3) North America (207Mcbm), 4) Middle East (93.3Mcbm), 5) Africa (48.9Mcbm), 6) South America (47.8Mcbm), and 7) Oceania (4.7Mcbm).
Analyzing this list some remarkable conclusion can be taken:
-The Middle East will show the strongest growth rate with 84% in 2020 as capacity in this regions grows from 50.8Mcbm to 93.3Mcbm;
-Africa will leapfrog South America and take position 5. This continent shows a growth rate of 12%. Storage capacity increases from 43.6Mcbm to 48.9Mcbm.
-Europe will grow by 4% till 2020 and is the slowest growing region of all the 7 regions. Capacity in this region grows from 235Mcb to 244Mcbm
Although, looking at regions is sort of looking at it as from a macro-level perspective, we can well say that the Middle East will be the hottest tank terminal location in 2020. There are some interesting locations in the Middle East that have a substantial part in the additions in this region.
Fast growing areas in the Middle East
Oman Tank Terminal in Raz Markaz
In Oman storage of oil liquids is concentrated around the ports of Salalah, around Oman’s capital Muscat and Sohar’s industrial area. Oman’s government owned investment company OOC, Oman Oil Company announced a major investment in 2012 on building a massive 31Mcbm crude storage facility in Ras Markaz. Some 200 tanks will be added. Estimates are that this terminal will be operational as from June 2019. With this investment Oman is trying to develop its position as an important global trading and storage hub.
South Oil Company in Iraq
Roughly said, Iraq has storage facilities in its oil fields in the North, around Kirkuk, Al Anbar and Erbil and in the South, around Basrah. Most of these terminals are controlled by the Ministry of Oil of the Republic of Iraq. Government-owned South Oil Company will add 2.78Mcbm of crude capacity in Al Zubair and another 0.464Mcbm in Fao. For the first addition applies that some 489 crude tanks will be built. December 2019 has been pointed as data of operation. For the latter, applies that 5 tanks will be built and this expansion is planned to become operational in December 2020.
Jask Oil Terminal in Iran
In Iran, storage facilities are controlled by state-owned Iranian Oil Terminals CO. These terminals are mostly located at the Persian Gulf and the gulf of Oman, connected with each-other by the infamous Strait of Hormuz. Not in the 2019 and 2020 numbers but definitely worth mentioning is the 10Mcbm crude addition in Jask. Jask is peninsula that runs into the Gulf of Oman. The Jask Oil Terminal will include 20 tanks with floating roofs. he terminal will also include loading and unloading wharves, offshore facilities including three single-point mooring (SPM), and other infrastructure for import/export oil. Estimates are that this addition will be active in December 2021.
The data for this article was gathered with the support of tankterminals.com’s database platform. With only a few clicks and couple of seconds the information of the biggest market players in the various regions was obtained.
For more information, contact: Jacob van den Berge, Head of Marketing & Sales Insights Global
GDPR Consent
Our website uses cookies. Click on the 'Accept all' button to accept the cookies and on the 'Settings' button for more information and settings.