Rhine freight market outlook: A week of fluctuating waters and stable strategies

By Lars van Wageningen, Research & Consultancy Manager

Over the past week, the Rhine barge freight market has demonstrated a delicate balance between operational resilience and environmental volatility. Insights Global’s daily freight reports from May 7 to May 12 reveal a market where water levels, logistical challenges, and booking behaviors shaped a nuanced trading environment. Below, we explore the main developments and what they signal for barge operators and traders moving forward.


1. Market Stability Masking Tactical Adjustments

At a glance, rates remained relatively stable throughout the week for most destinations, with only marginal day-to-day adjustments. However, a deeper look shows that this stability is underpinned by a series of tactical decisions by both importers and barge operators.

  • Early in the week, lower freight rates—particularly driven by a short-lived wave of higher water levels at Maxau—encouraged opportunistic bookings.

  • Later in the week, negotiations often stalled due to uncertainty about draft limitations as water levels began to recede again, affecting loaded volumes and contributing to more cautious planning.

Takeaway: The apparent calm belies a market where participants are carefully timing their engagements based on short-term hydrological shifts and terminal availability.


2. Water Levels and Freight Sensitivities

Water levels along key measuring stations like Kaub and Maxau remained a central concern. After a brief increase, forecasts indicated a consistent downward trend by week’s end, particularly at Kaub, where the draft is a critical factor for larger barges.

  • Water draft limitations directly impacted loadable volumes, which in turn influenced freight rates due to reduced economies of scale.

  • The variability in draft conditions contributed to a widening of rate differentials, especially for long-haul routes into Switzerland, where rate adjustments became more pronounced.

Takeaway: In a river system like the Rhine, where operational efficiency hinges on water depth, even minor fluctuations can result in noticeable shifts in freight economics.


3. Terminal Delays and Logistical Constraints

While ARA port congestion showed some signs of easing at the beginning of the week, significant waiting times persisted in key hubs like Amsterdam and Seatank Antwerp. As the weekend approached, new bottlenecks were reported in Bottrop and Gelsenkirchen, further complicating scheduling.

  • These delays continued to disrupt vessel turnaround and limited the availability of tonnage for fresh bookings.

  • The resulting uncertainty discouraged some participants from engaging in new freight deals, even when rates appeared attractive.

Takeaway: Port performance remains a critical external factor affecting freight market fluidity, and its ripple effect on pricing and availability should not be underestimated.


4. Basel: The Outlier Destination

Among all destinations, Basel stood out for its notable rate movements. Midweek saw a moderate correction, but by Monday, deals for Basel exhibited higher average values again, likely in response to reduced loading capacity caused by the river’s decreasing depth.

  • The week closed with Basel as the only destination with a marked uptick in rates, contrasting with the general trend of flat or softened pricing elsewhere.

Takeaway: Basel continues to act as a barometer for upstream logistical strain, often amplifying the effects of hydrological and operational constraints seen elsewhere on the Rhine.


5. A Week Defined by Selective Activity

With only a handful of deals concluded daily—ranging from four to eight across the week—the overall market was relatively quiet in transactional terms, but not inactive in strategic positioning.

  • Buyers focused on securing volumes ahead of the summer season, while barge owners looked for windows of improved loading efficiency.

  • Freight rates for gasoil and gasoline showed some directional divergence depending on product-specific demand and route characteristics.

Takeaway: Despite low transaction volumes, the week reflected a market in motion—quietly reshaping itself under the pressures of seasonality, river conditions, and infrastructure reliability.


Looking Ahead

As we move deeper into May, attention will remain firmly fixed on Rhine water levels and terminal throughput performance. For barging professionals, the key lies in maintaining flexibility—both in routing and in scheduling—to navigate this complex matrix of variables. In this dynamic environment, being well-informed is not just advantageous—it’s essential. As always, Insights Global continues to monitor and interpret these movements to support smarter, faster, and more resilient decisions in liquid bulk logistics.
European refining margins lagging, more closures expected?

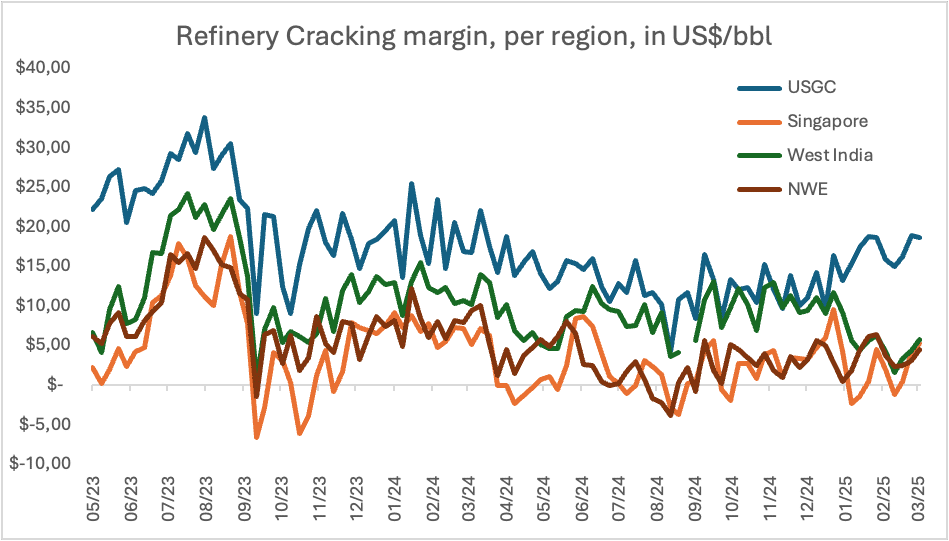
As of April 2025, Europe’s refining industry is navigating a landscape of further diminishing margins, influenced by a combination of economic pressures, policy shifts, and global competition. This downturn is prompting significant strategic adjustments within the sector, which is already coping with various closures seen in the past months and more to come for 2025 and beyond.

Current State of European Refining Margins

In 2024, European refining margins experienced a notable decline. Northwest Europe’s ultra-low sulphur diesel margins, for instance, decreased from $42 per barrel in 2022 to $29.71 per barrel in 2023. Its cracking margins remained on low levels during 2023 and 2024 which means the region could no longer remain competitive compared to other key regions. This downward trend is also attributed to factors such as reduced local European demand due to the energy transition and electrification, increasing competition from new refineries worldwide, and elevated operating costs stemming from stricter emissions regulations. ​

Potential Consequences

The sustained pressure on margins is leading to significant restructuring. For example, ExxonMobil announced plans to downsize operations at its Port-Jerome complex in France while BP is scaling back its Gelsenkirchen refinery in Germany by a third (and open for interested buyers to acquire the facility). Ineos will shut down its Grangemouth refining this spring and Shell has turned off the crude distillation units at its Rheinland Wesseling site in March, which could drop total refining capacity in the Northwest European region by 650.000 bpd. This could weaken the European competitiveness of the region and increases its reliance on imports from other regions, increasing vulnerability to and volatility of prices, product availability and importance of the supply chain.

The introduction of tariffs and changing trade policies are reshaping global oil flows. European refiners may find opportunities in markets previously dominated by U.S. exports, but also face heightened competition from new refineries in regions like West Africa (Nigeria, Angola) and Latin America (Mexico, Argentina). This is already leading to a downturn in gasoline export out of key hubs in ARA and a steady flow of (more cost-effective) jet fuel from Nigeria’s Dangote refinery to the US Gulf Coast.

European refiners are increasingly investing in renewable energy projects to align with the energy transition. However, falling profits are testing the viability of these green initiatives, with various projects facing delays or cancellations due to economic constraints. ​The latest examples include postponing SAF production by BP in its Spanish refinery and various (green) hydrogen initiatives in the region.

In conclusion, Europe’s refining sector is at a pivotal juncture, contending with declining margins and the obligation to adapt to a rapidly evolving global energy landscape.  Strategic decisions made now will be crucial in determining the future resilience and competitiveness of the industry.

Barge volumes, prices, & disruption: navigating the impact of NW Europe refinery closures

Refinery closures in North-West Europe are triggering significant shifts across the liquid bulk supply chain. With capacity reductions and structural changes taking place, market participants are facing growing uncertainty in product availability, trade flows, and barge utilization.

Clean ammonia market outlook: risks, realities, and infrastructure opportunities

By Patrick Kulsen, CEO, Insights Global

As the global push for decarbonization accelerates, clean ammonia has emerged as one of the most promising hydrogen carriers. Yet, beneath the optimism lies a complex and uneven market landscape—especially for those in the tank terminal industry.

During the Clean Ammonia Storage Conference in March 2025, we shared critical insights on the current state and future of clean ammonia, with a focus on storage dynamics. Here’s what tank terminal professionals need to know now.

Clean ammonia today: trade is decreasing

Ammonia is primarily used in fertilizer production—but clean ammonia (produced with renewable energy or low-carbon hydrogen) is increasingly eyed for applications in power generation, shipping fuel, and as a key enabler of the hydrogen economy.

Global demand has remained stable, with significant import needs across Asia, North-Africa, Europe, and North America. Independent storage infrastructure is still small compared to global trade of 15Mton. Our research shows that current global ammonia tank terminal capacity sits at approximately 1.35 million cbm, with Europe holding the largest share.

Trade flows are evolving—but terminal readiness is uneven

Ammonia trade flows remain concentrated, with major exports from countries like Trinidad and Tobago, Saudi Arabia, and Indonesia. Imports are dominated by India, Morocco, and the U.S.. This concerns mainly gray ammonia, produced from fossil fuels. The big promise is the development of green ammonia supply chains as part of the energy transition.

However, many planned terminal projects, aimed at facilitating these green ammonia flows, remain in early development stages—often lacking final investment decisions (FIDs), clear start dates, or capacity details. According to plans a wave of projects will come online between 2026 and 2030, adding at least 0.9 million cbm of capacity, particularly in Europe.

Market headwinds: Project realization rates are low

Despite aggressive decarbonization goals, less than 10% of green ammonia and hydrogen projects have been realized so far. Why? High production costs, limited offtake commitments, and an overall lack of willingness to pay premium prices.

Adding to the challenging investment environment is the recently installed Trump administration which is reshuffling priorities away from the energy transition to “drill-baby-drill”.

For tank terminal stakeholders, this translates into uncertainty—but also opportunity. The market may be slower than hoped or go in other directions, but those who anticipate infrastructure needs now stand to benefit most when momentum returns.

What’s next for tank terminals?

Terminal operators should carefully monitor developments in:

  • Green corridors for maritime shipping

  • Industrial hubs planning hydrogen/ammonia integration

  • Emerging regulations supporting clean fuel mandates

Storage players with flexibility and the ability to scale quickly will be best positioned to support the evolving ammonia supply chain.

Get the tools to stay ahead

At TankTerminals.com, we track ammonia terminal projects worldwide—planned, operational, and everything in between. Our platform gives professionals a data-driven edge in planning, benchmarking, and opportunity spotting.

👉 Start your free trial today and see how our research tool can support your ammonia market strategy.

The outlook for European liquid bulk logistics sector in 2025

The European liquid bulk sector, consisting of tank storage, tanker vessel and barging transport logistics, is dependent on global trade and is therefore influenced by geopolitics. Looking at current developments we conclude that there is a shift from globalization to global competition. The three major economic blocks, the US, China and the EU, are increasingly competing for economic power. In this race the EU is falling behind. The reason for this lag in economic development can be attributed to high energy prices, a strategic dependence on imports of critical raw materials, a poor track record of breeding high value innovative technology companies, and complicated, slow and indecisive decision making processes in the EU Council.

The report on EU competitiveness made by Draghi pinpoints three transformations that are needed to increase competitiveness: accelerate innovation and find new growth engines, bring down high energy prices while continuing to decarbonise, and cope with instable geopolitics by reducing dependencies and increasing defence investments. For Energy Intensive Industries and the transport sectors in Europe the report formulates a number measures along this line. Generally speaking the measures aimed at combatting high energy prices, aimed at supporting the automotive sector and aimed at spurring investments in chemical business and hydrogen are positive for tank storage and liquid bulk transport companies as business in chemical industries is supported. Hopefully these measures will be a priority for the European Commission and the European Council in the months and years to come. Much is at stake: our wealth, independence and way-of-life are under threat!

Short term market fundamentals are less favourable for tank storage and tanker transport markets. Oil prices are less volatile and the market is in backwardation. Natural gas prices are about four times as high compared to US markets leading to high marginal cost levels compared to other major competing regions. Petroleum refining and steam cracking margins are also depressed. The bearish market sentiment has translated into a lot of announced closures in Europe. Refineries and chemical plants across the continent are closing operations in a push to rationalize capacity. The effect on business is negative as this means less transport volumes and thus less need for tank storage capacity and shipping capacity. Our research has already confirmed decreasing tank storage rates and freight rates compared to previous periods. 2025 is set to become a difficult year for the liquid bulk supply chains and logistical operators in Europe.

To download the full slide pack please fill in the form below.

Insights Global / PJK International successfully completed 2nd independent assurance review of ARA CPP and Rhine Barge Freight Rate benchmark prices

Insights Global / PJK International has successfully concluded its second external assurance review of its benchmark prices for ARA CPP and Rhine Barge Freight Rates.

The independent review, conducted by an external auditing firm, assessed the policies and processes used by Insights Global / PJK International to evaluate oil product transportation costs via inland barges in Northwest Europe.

These policies and processes were developed in alignment with the Principles for Price Reporting Agencies (PRAs) established by the International Organization of Securities Commissions (IOSCO) in October 2012.

Recognized by the G20 in November 2012, the IOSCO PRA Principles have been incorporated into the EU Benchmark Regulation (BMR).

These principles set comprehensive standards for governance, quality, integrity, control, and conflict management for commodity benchmark price assessments.

Compliance with these standards requires annual external audits. Insights Global’s price assessment methodologies and policies are available here.

The audit report can be provided upon request.

Patrick Kulsen’s exclusive interview with Inspenet: a deep dive into Insights Global’s market expansion

We are excited to announce that Insights Global is featured in an exclusive interview with Inspenet. This interview provides an in-depth look at our strategic initiatives, market insights, and our plans for expanding our presence in the U.S. market. Learn from our experts as they discuss the future of the liquid bulk and terminal industry, and how our advanced data-driven solutions are shaping the landscape. Don’t miss this opportunity to gain valuable knowledge and stay ahead in the industry.

In this interview, Patrick, our Managing Director, delves into the evolution of our company from its European origins to becoming a global leader. He shares insights on our commitment to innovation, the challenges and opportunities in the liquid bulk sector, and our vision for the future. This candid conversation is a must-watch for anyone looking to understand the dynamics of the industry and how we are positioning ourselves to provide unparalleled value to our clients worldwide.

Watch the interview here.

CITGO Petroleum Corporation Prices $1.10 Billion Senior Secured Notes

CITGO Petroleum Corporation (“CITGO”) has priced $1.10 billion aggregate principal amount of 8.375% senior secured notes due 2029 (the “notes”) in a private offering exempt from the registration requirements of the Securities Act of 1933, as amended (the “Securities Act”). The closing of the offering is expected to occur on September 20, 2023, subject to customary closing conditions.

CITGO intends to use the total net proceeds from the sale of the notes for general corporate purposes and to pay all fees and expenses in connection with the sale of the notes.

In addition, CITGO intends to pay a dividend to CITGO Holding, Inc. (“CITGO Holding”) of approximately $1.120 billion to fund the pending redemption of the $1.286 billion aggregate principal amount of CITGO Holding’s 9.25% senior secured notes due 2024 (the “CITGO Holding notes”).  The redemption of the CITGO Holding notes is contingent upon the consummation of the notes offering.

This press release does not constitute an offer to sell or the solicitation of an offer to buy the notes, nor will there be any sale of the notes in any state or other jurisdiction in which such offer, solicitation or sale would be unlawful.  This press release does not constitute a notice of redemption with respect to the CITGO Holding notes.

The offer and sale of the notes have not been and will not be registered under the Securities Act, or the securities laws of any other jurisdiction, and may not be offered or sold in the United States absent registration or an applicable exemption from registration requirements.

The notes are being offered only to persons reasonably believed to be qualified institutional buyers under Rule 144A under the Securities Act and to non-U.S. persons in offshore transactions in compliance with Regulation S under the Securities Act.

By PR News, September 29, 2023

An Oil Boom Is Underway In Ghana

Several African countries have welcomed investment in oil and gas in recent years, as parts of the continent undergo industrialization and investors look to develop new reserves. Africa provides companies with the potential for low-cost, low-carbon oil and gas in largely unexplored areas.

But governments across the region hope to be more closely involved in operations, ensuring that they get a significant proportion of the revenues to bolster their economies. One such country is Ghana, which expects an oil boom over the next decade and beyond. 

At the COP27 climate summit last year, several African state leaders presented the case for the development of the region’s oil and gas resources. Following a year of shortages and surging energy prices, several countries with oil and gas potential urged investors to develop new, low-carbon operations to meet the global demand without having to rely on aging, carbon-heavy operations. And many energy firms are now viewing regions such as Africa and the Caribbean as vital to their aims to decarbonize. 

In Ghana, there are 17 oil and gas projects in the 2023 to 2027 pipeline. This includes 3 upstream projects, nine projects in the midstream sector, and five new downstream projects.

Ghana is now one of Africa’s fastest-growing hydrocarbon producers. There are several oil operations already underway in the West African country, with Phase 1 of the Pecan Conventional Oilfield as well as the Jubilee South East field and Ntomme Far West Development. 

Pecan is expected to have a capacity of 82,500 bpd when production begins in 2025, with phase 1 costing $1.5 billion. It is operated by exploration and production company Aker Energy Ghana Ltd. (50%); petroleum corporation Lukoil (38%); Ghana’s state-owned Ghana National Petroleum Corporation (GNPC) (10%); and transport company Bulk Ship & Trade (2%). Meanwhile, the Jubilee South East field should begin producing 37,000 bpd by the end of the year. The field is operated by Tullow Oil (38.98%), deepwater exploration and production company Kosmos Energy (38.61%); the GNPC (19.69%); and South Africa’s National Oil Company (NOC) PetroSA (2.72%). Ghana hopes to discover further oil and gas deposits in the Ntomme Far West Development, with a pre-feasibility analysis having taken place and exploration drilling planned for later this year. 

Meanwhile, the country’s midstream sector will expand alongside exploration and production operations. Ghana plans to develop the Tema Floating Liquefied Natural Gas (FLNG) Plant, the Tema VI Liquids Storage Terminal, the Dixcove Oil Storage Facility, the Wa Oil Storage Facility and the Tema-Akosombo II and Tema Pipelines between 2023 to 2027. 

In March this year, the African Energy Chamber stated that Ghana hopes to double its oil output by the end of the year, from 180,000 bpd to 420,000 bpd. The CEO of the Petroleum Commission of Ghana, Egbert Faibille Jr., stated “Ghana has positioned itself to attract investments in the energy sector.

We present one of the best investment opportunities in the sub-region. Following the Jubilee discovery in 2007, 30 additional discoveries have been made and are pending appraisal and development. Ghana guarantees attractive fiscal terms. These terms have proven over the years to provide a favorable investment framework.” Faibille added, “We have several blocks open for direct negotiation and three available for farm-in opportunities.

We have some fields that are in pre-development, so if we are able to get contractors, we should see a surge in production by 2030.”

Ghana’s oil operations are already well underway, with the country expecting to open a new $1.98 billion oil refinery in Tema this month.

The Sentuo Group’s facility is expected to produce 5 million metric tonnes of petroleum products including liquified petroleum gas (LPG), jet fuel, gasoline, diesel, and fuel oil. Ghana’s Minister of Trade and Industry confirmed last month that Sentuo is in discussions with the government to acquire 500,000 barrels of crude for refining.

By 2025, Sentuo plans to expand the facility to refine 4.26 million tonnes of petroleum products. 

Meanwhile, Britain’s Tullow Oil announced the start of operations at the Jubilee South East (JSE) project in July. The company said that the first well started producing, with another two producers and a water injector expected to come online later in the year. Tullow hopes the field will produce over 100,000 bpd once operational.

The firm’s CEO stated, “Successful start-up at Jubilee South East is a significant milestone for Tullow and for Ghana.” He added, “We are well positioned for future growth with production ramping up in the second half of 2023 that will generate significant free cash flow.

This marks the start of material deleveraging as we continue our transition into a low-debt business with the financial flexibility to pursue value accretive opportunities.” 

Ghana is viewed as Africa’s rising star, thanks to its stable political system, growing economy, and the rapid development of its oil and gas sector.

There are several projects in the pipeline, with oil production expected to increase significantly by 2030. Ghana could provide oil producers with the opportunity to develop the low-cost, low-carbon oil needed to meet the high global demand en route to an eventual global energy transition.

OilPrice.com by Felicity Bradstock, August 23, 2023

Nigeria Looks To Attract Oil & Gas Investment At International Roadshow

Nigeria plans to hold an international roadshow to attract investments in its upstream sector, the petroleum regulator of OPEC’s biggest African oil producer said in a speech shared with Reuters.

The Nigerian Upstream Petroleum Regulatory Commission (NUPRC) plans to organize in the coming weeks an international roadshow to pitch upstream investments in the country, which looks to boost its oil production and significantly raise its natural gas output.     

NUPRC plans to organize in the coming weeks its first Nigerian Upstream International Investment and Financial Roadshow (NUIIFR) to allow upstream players to network and discuss financial structures to enable investment, representatives of the regulator said in a speech at a conference of the Society of Petroleum Engineers in Lagos earlier this week.

“Whereas the global imperatives for energy transition is clear and justified, the need for Africa’s energy security, economic development and prosperity cannot be overemphasised,” the Nigerian regulator said.

Nigeria aims to significantly increase its oil production to up to 1.7 million barrels per day (bpd) by November 2023, hoping to win a higher quota in the OPEC+ agreement, Gabriel Tanimu Aduda, Permanent Secretary at Nigeria’s Ministry of Petroleum Resources, told Energy Intelligence last month.

Nigeria has consistently failed to produce to its quota in the OPEC+ agreement. The combination of pipeline vandalism and oil theft with a lack of investment in capacity has made Nigeria the biggest laggard in crude oil production in the OPEC+ alliance. Oil theft and pipeline vandalism have long plagued Nigeria’s upstream oil and gas industry, driving majors out of the country and often resulting in force majeure at the key crude oil export terminals.

Nigeria’s quota was 1.742 million bpd earlier this year, but due to its underproduction of more than 400,000 bpd, the output cap for Nigeria was lowered to 1.38 million bpd at the OPEC+ meeting in early June.

Oilprice.com by Charles Kennedy, August 8, 2023

One Sector To Watch Oil As Oil Prices Rally

After remaining range-bound for much of the second quarter, oil prices have mounted a significant rally, with analysts saying oil markets are finally waking up to the fact that fundamentals have tightened significantly. After remaining in surplus for months, many experts have predicted that demand will begin to surpass supply thus improving oil prices and margins for oil refiners.

For instance, StanChart’s demand model projects a supply deficit of 2.81 million barrels per day in August; 2.43 mb/d in September and more than 2mb/d in November and December.

The analysts have also projected that global inventories will fall by 310 mb by end-2023 and another 94 mb in the first quarter of 2024 thus pushing oil prices higher.  

Although U.S. oil refinery margins have halved since the middle of 2022, they remain at historically high levels and are likely to remain elevated through the summer of 2023 thanks to high operating rates and low fuel stocks.

Gross margins for refining three barrels of crude to produce two barrels of gasoline and one barrel of distillate fuel oil have retreated to $33 per barrel from a record $60 at the start of June 2022. Still, margins are in the 95th percentile for all trading days since 2001, underpinning refinery profitability and encouraging high levels of capacity utilization. 

Revenues and profits for refining companies have declined from last year’s historical highs but remain at healthy levels. Here are three refining stocks to keep an eye on.

Marathon Petroleum Corp

Market Cap: $54.3B

Dividend Yield: 2.6%

YTD Returns: 22.5%

Marathon Petroleum Corporation (NYSE:MPC) is an integrated downstream energy company and the largest petroleum refinery operator in the United States. The company’s latest earnings revealed strong refinery demand despite general economic malaise. Marathon’s Q2 2023 revenue of $36.82B (-32.1% Y/Y) beats the Wall Street consensus by $2.94B while GAAP EPS of $5.32 beat by $0.74.

Net income fell to $2.23B, or $5.32/share, from $5.87B, or $10.95/share from a year ago while adjusted EBITDA was cut in half to $4.53B from $9.06B a year ago. Refining & Marketing segment adjusted EBITDA fell to $11.88/bbl from $27.79/bbl for the prior-year quarter while segment margin was $22.10/bbl compared with $37.54/bbl in last year’s corresponding quarter.

Crude capacity utilization clocked in at 93% with total throughput of 2.9M bbl/day.

Marathon Ol continues returning copious amounts of cash to shareholders: The company revealed that it returned ~$3.4B of capital through $3.1B of stock buybacks and $316M of dividends in the second quarter. The company’s diversification into renewables gives Marathon Oil better protection from fluctuating oil prices and refining margins.

PBF Energy Inc.

Market Cap: $6.0B

Dividend Yield: 1.3%

YTD Returns: 26.2%

PBF Energy Inc. (NYSE:PBF) engages in refining and supplying petroleum products. PBF is one of the youngest oil refiners in the United States having been created in 2008. The company released its quarterly earnings report on Thursday, with revenue of $9.16B (-34.9% Y/Y) beating by $230M while Q2 Non-GAAP EPS of $2.29 beat by $0.05.

In-line with the industry trend, Q2 net income fell to $1.02B, or $7.88/share, from $1.2B, or $9.65/share, in the year-earlier quarter.  production fell slightly to 945,700 bbl/day from 958,800 bbl/day a year earlier. Refinery throughput fell to 935,800 bbl/day from 958,800 bbl/day a year ago and expects full-year production to average 915K-975K bbl/day.

And, just like its bigger peer, PBF Energy is diversifying into renewables: the company announced it had begun operations at its St. Bernard renewable fuel joint venture in New Orleans, and managed to sell the first products from the facility in July. The 50-50 joint venture with Eni S.p.A.(NYSE:E) has a processing capacity of ~1.1M tons/year of raw materials and will produce ~7.3M bbl/year of renewable diesel.

Phillips 66

Market Cap: $48.5B

Dividend Yield: 3.9%

YTD Returns:9.0%

Phillips 66 (NYSE:PSX) is one of the oldest refineries in the United States. The company operates as an energy manufacturing and logistics company, with its refining segment one of its largest. Phillips 66 reported Q2 Non-GAAP EPS of $3.87, beating the consensus by $0.31.

The company does not report revenue figures but said it generated $1.0 billion of operating cash flow ($2.0 billion excluding working capital).  Realized refining margins fell to $15.32/bbl from $28.62/bbl a year ago. Phillips 66 revealed that it plans to run its refineries in the mid-90% range of their combined crude oil throughput capacity of 1.9M bbl/day in Q3, close to second quarter’s figure at 93%.

Phillips 66 announced that its Rodeo refinery in California will be fully converted to renewable diesel production by the first quarter of 2024 when it is scheduled to begin commercial operation.

Oilprice.com by Alex Kimani, August 8, 2023